Resources
Reports and analysis on getting connected.
-
Grid Access for Growth
Twelve business groups set out five challenges facing the businesses that depend on the grid, and what is still needed to fix them.
Read the report -
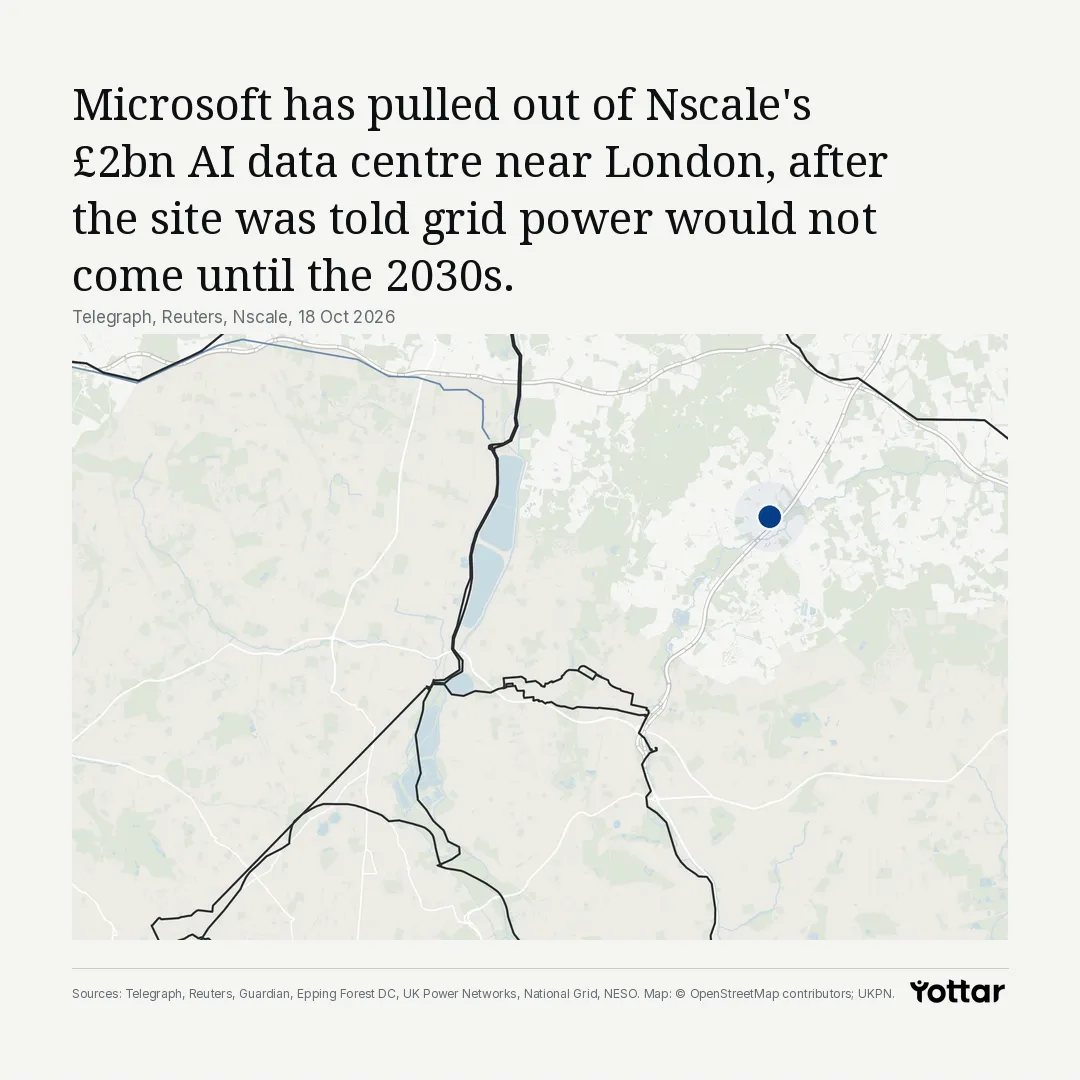
Nscale's Loughton data centre: what the grid data shows
Microsoft has reportedly pulled out of Nscale's £2bn AI data centre near London. We looked at why, using the data we can source.
Watch the video
Reports
Posts
-
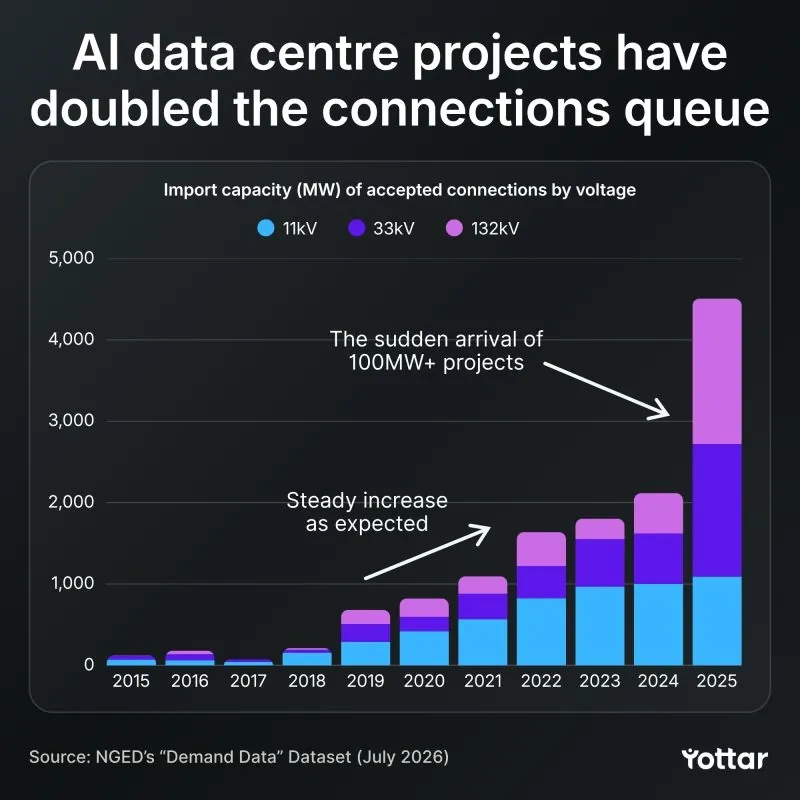
Data centres are rewriting the distribution demand queue
Accepted connections at the higher distribution voltages doubled from 2024 to 2025, with single sites seeking 80MW to 350MW of import capacity. Hard to see what else that could be but AI data centres, and hard to overstate the build-out it implies.
Read the post -
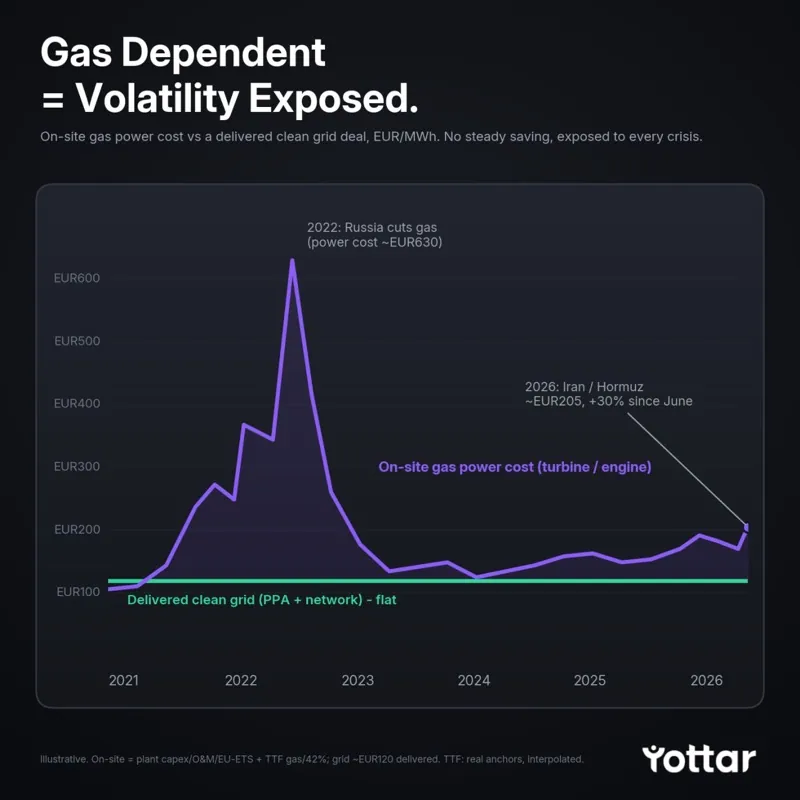
Sovereign AI on imported gas isn't sovereign
On-site gas looks like the fast route past the connection queue, but it turns a data centre into a gas buyer carrying fuel, carbon and commodity risk. The real fix is seeing where the grid can connect sooner, with fewer reinforcements.
Read the post -
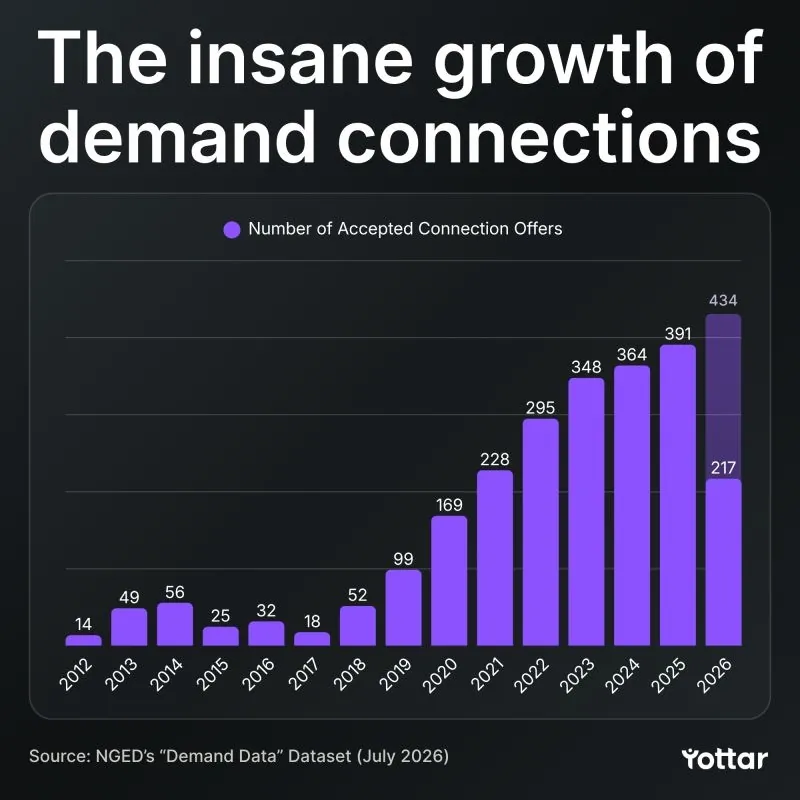
The growth in accepted demand connections is unprecedented
NGED's newly published demand connections register shows accepted 1MW+ connections rising steeply since 2020 with no sign of slowing. These are large HV and EHV connections, and the volume raises a real question about how the networks are expected to keep up.
Read the post -
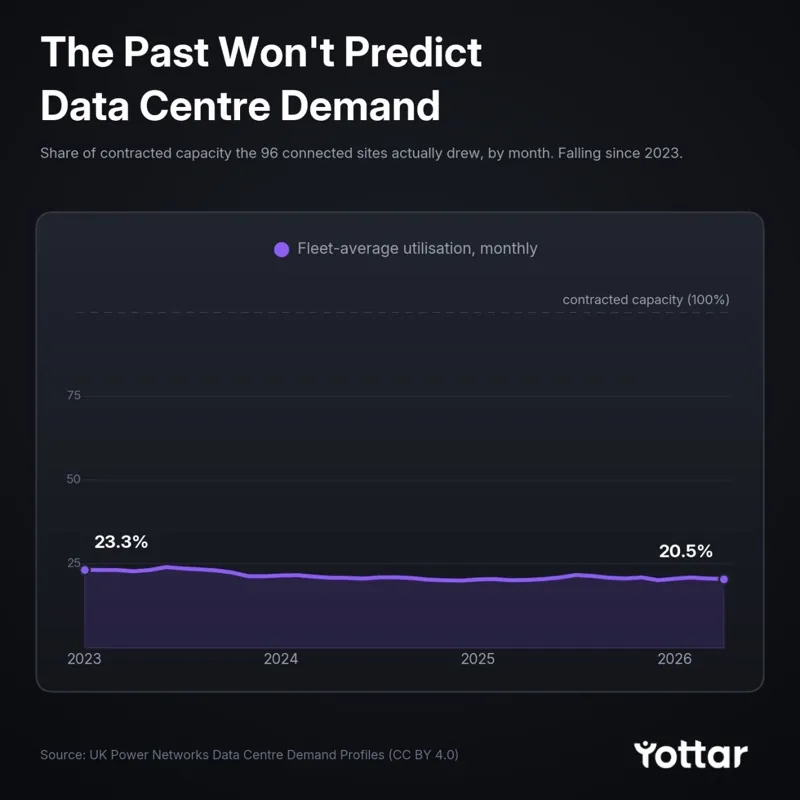
Data centres draw a fifth of the capacity they contract
UKPN's half-hourly profiles for 96 connected data centres show the fleet averaging 20.8% of agreed import capacity; its busiest half-hour in 40 months hit 26.5%. Neither history nor contracted MW alone can plan for the AI demand now in the queue.
Read the post -
Clean power is cheap power, but the pathway needs explaining
The 2026 CfD auction cleared solar and wind well below the cost of gas generation, yet bills stay high because gas still sets the price. Clean Power 2030, plus a more visible and better coordinated grid, is the route to actually cutting them.
Read the post -
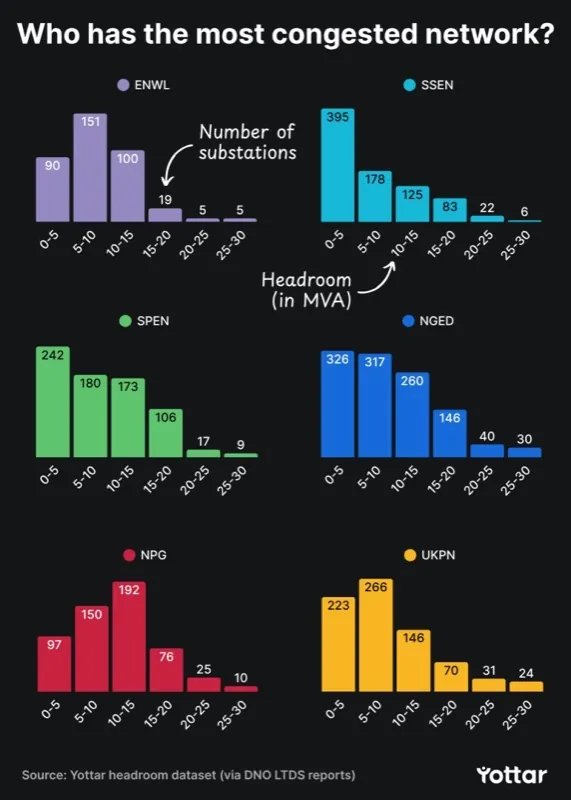
Which DNO has the most congested network?
Spare capacity at the typical primary substation varies sharply by DNO: nearly half of SSEN's primaries have under 5MVA spare (August 2025 data), while NPg has the most headroom. With typical HV demand projects at 1-5MVA, what's left won't stick around long.
Read the post